
At a media stand-up last week the Minister of Finance made the claim that any fuel disruption was “at least three to four weeks away”, and that Treasury had advised her that in the “worst case scenario” inflation may reach 3.7%.
The Minister has since clarified that these comments were based on specific assumptions about prior levels of impact to infrastructure, but there aren’t any further updated projections on what’s kind of cost of living pressure is coming down the pipeline for NZ households.
I did submit an official information request to Treasury for that advice, however it’s a well-established fact that oil markets move much quicker than official information, so it may all be ancient history by the time I get a response.
The latest CPI release shows that petrol alone accounts for 3.5% of the basket of goods and services that Stats NZ measures. The wider group including diesel, oil, and gas represents 4.3% of the basket. Three years earlier, when fuel prices were running hot off the back of Russia’s invasion of Ukraine, they were 4.88% of the basket.
Last week reporting suggested NZer already faced a 20% jump at the pump (from around $2.50 for a litre of 91 to around $3). Fuel monitoring site gaspy is now showing an average 91 price of $3.35, suggesting an increase closer to 35%.
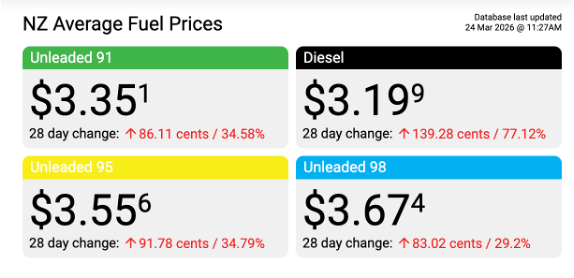
The impact of a price change on the total CPI is calculated as the weight of the item in the CPI basket (3.5%) multiplied by the change in price. A 35% increase on 3.5% of the basket indicates a 1.23% increase on the CPI, which was already sitting at 3.1% in the December 2025 quarter. If the 35% increase applied to all oil, diesel, petrol, and gas products (4.3% of the basket) then this would mean a 1.5% increase – lifting CPI inflation to 4.6%.
This is a pretty crude calculation, and it’s worth noting that Treasury had previously been picking a CPI of 2.5% in March 2026. Add 1.5% to that and we’re at 4%, already past the worst case scenario that Willis had mentioned.
And that is just adding in the cost of one set of price changes across the first few weeks of this crisis. It also assumes that fuel price hikes don’t leak through into other goods like fertiliser and food, a frankly heroic assumption.
Obviously don’t take my word for it. On 17 March ANZ moved their central CPI forecast to 3.6% in Q3, in line with BNZ. I suspect there is more to come.
One recent peer-reviewed study on the impact of fuel pricing on general inflation in New Zealand suggested that an increase in headline inflation immediately after a “10% petrol price shock was around 12%”. It’s not clear if that response is linear (i.e. does a 35% increase leads to a 42% inflation rate increase).
Of course petrol pricing doesn’t hit all households equally. The Household Living-cost Price Index (HLPI) shows us that petrol pricing impacts the wealthiest the least, and hits middle-income households – who often have to drive to get to work – the most. The poorest households feel the pain of petrol pricing more than the wealthiest.
Petrol isn’t the only good affected by the closure of the Strait of Hormuz. Diesel, LNG, fertiliser, sulphur, bitumen, helium, urea and many others. Many other goods produced by countries with oil from the area – notably plastics – will also be impacted. These second-round impacts will persist even after the conflict in the area is resolved and resources are flowing normally.
The government’s decision to procure an LNG terminal to back up our electricity system in dry years is now looking particularly short-sighted, with prices now more than double pre-war levels and damage to the world’s largest LNG facility reducing global supply for 3-5 years. The Minister of Energy yesterday confirmed that he is committed to this decision.
And, to top it off, MBIE has temporarily stopped publishing the weekly fuel price monitoring data, which allowed us to track the margin petrol companies generated from their retailing operations. Using this data in 2022 the government was able to ensure decreases in importer costs were passed through to consumers.
Kiwis are still reeling from the global inflation spike in 2021-22 and the fiscal austerity that followed. They know that prices are rising, that rates may follow, and that life will get more expensive. It would be helpful if the Minister of Finance could communicate what the officials are telling her.
Exogenous price shocks can't and shouldn't be dealt with in a similar manner to endogenous inflation. The point if interest rate rises in this context is to ensure that the associated costs are disproportionately loaded onto net debtors rather than net creditors i.e. yet another way of robbing the poor to pay the rich.
The argument that Keynesian economics didn't have an answer to exogenous inflation was the stalking horse for Neoliberalism in the late 1970's. Of course it was spurious.
Harold Wilson's 'Prices and Incomes' policy and later the Wilson / Callaghan 'Social Contract' was an attempt to deal with exogenous inflation by sharing out the cuts in living standards occasioned by the removal of value to outside of the domestic economy equally between capitalists and workers. As an attempt at a stability measure it took little consideration of the capacity of workers, and in many cases domestic non-financial businesses, to bear the burden of falling incomes. True to Keynes's own desire, the point was to preserve capitalism rather than replace it with socialism- which it did as a placeholder until the Neoliberals became ascendant- a fact that Keynes would have found at least as obnoxious as Socialism.
It beggars belief at this juncture that government is talking of this fuel crisis as an inflation risk problem rather than as an existential risk to civil society. Of course permission to do this comes straight out of the one-track-minds of NZ Treasury officials and their think-tank buddies. who are terrified to admit that there are 'other ways of doing things' during a crisis. Alternatives to forty years of 'There Is No Altenative' lies.
Moving somewhat towards a wartime command economy- the use of government's capacity for active management both material and fiscal would be entirely appropriate. These are, however, precisely the resilient managerial and intellectual capacities that Neoliberalism has deliberately purged from government's domain over many years to prevent them from being used 'to re-establish socialism'.
Hi Ed, have you looked at the possibility of fuel running out entirely for possibly months? Is this a realistic scenario?